How Does Social Tax Give Me Health Insurance in Estonia?
One of the most confusing moments for any new expat in Tallinn or Tartu is staring at a first payslip and seeing a massive chunk of money labeled as Social Tax. You might wonder where that money goes and why you still can’t seem to book a doctor’s appointment immediately. This guide explains exactly how Estonia’s social tax system funds your healthcare and the specific steps required to turn those tax euros into active medical coverage.
The Relationship Between Social Tax and Your Healthcare Rights
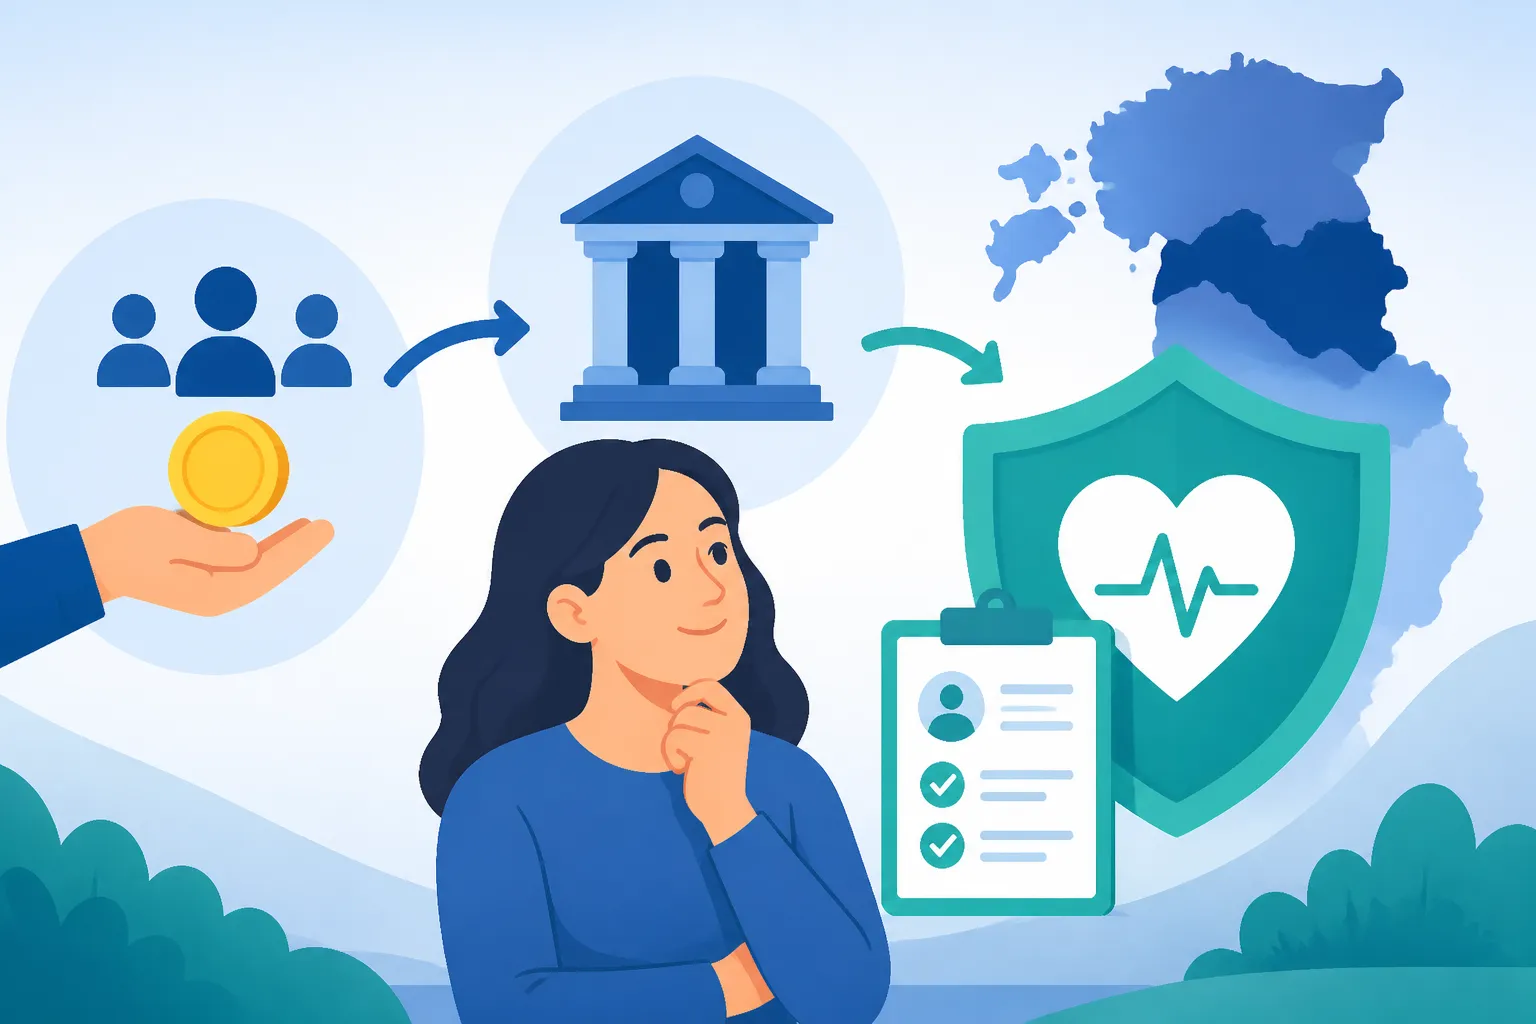
In many countries, health insurance is a separate premium you pay to a private company or a specific health fund. Estonia does things differently. Here, the system is built on a principle of solidarity, where the burden of funding the national healthcare system falls on the shoulders of employers and self-employed individuals through a mandatory levy known as the social tax. When you work for an Estonian company, you aren’t just earning a salary; you are essentially buying into one of the most advanced digital health systems in the world.
The social tax in Estonia is currently set at 33% of your gross salary. It is important to understand that this is not deducted from your gross pay, but rather paid by your employer on top of your gross salary. However, for those working as freelancers or sole proprietors, this 33% becomes a direct out-of-pocket expense. This 33% is not a monolithic block; it is split internally by the Tax and Customs Board. Specifically, 20% goes toward public pension insurance, while the remaining 13% is earmarked for public health insurance. This 13% is the magic number that grants you access to the Tervisekassa (the Estonian Health Insurance Fund).
Validation of the frustration is necessary here: it feels like a heavy tax burden, especially when you are a young, healthy expat who rarely visits a doctor. You might feel that the 13% is "lost" money if you don't use the system. However, the Estonian philosophy is that your contributions today support the elderly and the vulnerable, just as the contributions of others will support you if you face a major medical crisis or when you eventually reach retirement age.
The Employer Responsibility in the Tax Chain
If you are a traditional employee, your involvement in the tax process is almost non-existent, which is both a blessing and a curse. Your employer is legally obligated to register your employment in the Employment Register (Töötamise register) managed by the Tax and Customs Board. This registration is what triggers the flow of data to the healthcare system.
The moment your employer logs your start date and begins reporting your Understanding Social Tax and Pension Contributions in Estonia, the gears begin to turn. The Tax Board notifies the Tervisekassa that a new contributor has entered the system. For most expats, this is the primary way to gain coverage. If your employer fails to report your wages or tries to pay you "off the books," you lose your right to healthcare. This is why it is critical to ensure you have a formal contract and that your employer is reputable.
The Self-Employed and the Minimum Social Tax Obligation
For those of us who came to Estonia to join the startup scene or work as freelancers, the social tax becomes a much more visible hurdle. If you are an FIE (Sole Proprietor) or the owner of an OÜ (Private Limited Company) taking a board member salary, you are responsible for paying that 33% yourself.
There is a concept in Estonia known as the "minimum social tax obligation." To maintain health insurance, you must pay social tax on at least the monthly minimum rate established by the state budget. If you earn less than this threshold in a given month, you—or your company—must still pay the tax based on the minimum rate to keep your insurance active. This can be a significant financial strain during slow business months. Many digital nomads find that Understanding Health Coverage for the Self-Employed (FIE) in Estonia requires careful monthly accounting to avoid a lapse in coverage.
The Activation Timeline and the Infamous Waiting Period
One of the biggest shocks for new arrivals is that health insurance does not start the second you sign your work contract. There is a lag that catches many people off guard. Typically, your health insurance coverage begins after a 14-day waiting period from the date your employment was entered into the register.
I remember talking to a friend who moved from the US to Tallinn; he assumed he was "safe" the day he started his job. On day three, he came down with a severe case of tonsillitis and realized his Estonian insurance hadn't kicked in yet. He ended up paying the full "uninsured" price for a private consultation. This is a common pitfall. Because the Estonian system relies on tax data, there is a built-in delay to prevent people from only "joining" the system the day they get sick.
During this two-week gap, or if you are waiting for your residence permit to be processed, you are effectively flying without a net. This is where many expats choose to use temporary solutions like SafetyWing. Having a bridge policy from a provider like SafetyWing ensures that if you trip on the cobblestones of Old Town during your first week, you aren't stuck with a massive bill while waiting for the Tervisekassa to recognize your social tax contributions. SafetyWing is particularly useful because it is designed for people in transition, covering that awkward period before the local bureaucracy fully acknowledges your existence.
How to Verify Your Insurance Status
Because Estonia is a "paperless" society, you won't receive a physical insurance card in the mail. Your insurance is tied directly to your Isikukood (personal identification code). To check if your employer’s tax payments have successfully activated your coverage, you need to log into the state portal, eesti.ee.
Once logged in with your ID-card or Mobile-ID, you can navigate to the health section to see your status. If it says "Kindlustus olemas" (Insurance exists), you are good to go. If it says "Kindlustus puudub" (Insurance missing), then something has gone wrong in the communication between the Tax Board and the Tervisekassa, or your 14-day waiting period isn't over yet. Learning How to Get Your Isikukood (Personal Code) and Why It Matters for Healthcare is the absolute first step in this entire journey.
What Your 13 Percent Social Tax Contribution Covers
Once the status on eesti.ee turns green, a world of highly subsidized healthcare opens up to you. The social tax isn't just a fee; it's an all-access pass to a system that, while sometimes slow, is incredibly thorough.
The backbone of this system is the Family Doctor, or Perearst. In Estonia, you don't go to a hospital for a cold or a standard prescription; you go to your assigned doctor. Your social tax covers the full cost of visits to your Perearst. There is no "co-pay" for a standard appointment. However, the system is built on a "gatekeeper" model. To see a specialist, like a cardiologist or a neurologist, you generally need a referral (saatekiri) from your family doctor.
Comparison of Costs: Insured vs. Uninsured
To understand the value of your social tax, it helps to look at the price difference for common medical services. Without insurance, the costs can escalate quickly, even though Estonian "private" prices are often lower than those in Western Europe or North America.
| Service Type | Cost with Tervisekassa (Insured) | Estimated Cost Without Insurance |
|---|---|---|
| Family Doctor Visit | 0 EUR | 40 – 70 EUR |
| Specialist Consultation | 5 EUR (Standard Fee) | 80 – 150 EUR |
| Hospital Inpatient Stay | 2.50 EUR per day (up to 10 days) | 200+ EUR per day |
| Digital Prescription Fee | 2.50 EUR (plus discounted med cost) | Full Market Price |
| Emergency Room Visit | 5 EUR | 100 – 200 EUR |
As you can see, the 5-euro fee for a specialist visit is a symbolic gesture compared to the actual cost of the doctor's time and the equipment used. This is why Understanding the Cost of Healthcare in Estonia: A Complete Breakdown for Foreigners (2026) is so eye-opening for expats who are used to high insurance premiums and high co-pays.
The Role of Supplemental Insurance
Even with the social tax providing a robust base, many expats feel the public system's limitations. The most significant issue is the waiting list. For non-urgent specialist care, you might wait three to four months for an appointment. If you want to bypass these queues, you have to go to a private clinic and pay the full price yourself.
This is another area where many international workers keep an active policy with a company like SafetyWing even after their Estonian insurance is active. While Tervisekassa is great for long-term chronic care or major surgeries, SafetyWing can provide a layer of flexibility, especially if you travel outside of Estonia frequently or if you prefer the speed of private clinics that might not be fully covered by the public system. It acts as a safety valve for a system that can sometimes feel bogged down by its own success.
Social Tax for Students and Non-Working Residents
What if you aren't working? Does the social tax system leave you behind? Not necessarily, but the path to coverage is different. If you are a student at an Estonian university, the state effectively covers your "contribution." The government pays the social tax equivalent on your behalf, granting you full health insurance for the duration of your studies plus a short grace period after graduation.
For spouses of workers, the situation is more complex. Estonia does not have "family coverage" where one person's tax payment covers the whole household automatically. If your spouse is not working, they are not covered by your social tax unless they meet specific criteria, such as caring for a child under the age of three or being registered as unemployed and actively seeking work through the Understanding the Estonian Unemployment Insurance Fund (Töötukassa).
If your spouse does not fit into these categories, they will be considered uninsured. In these cases, you have two options: pay for voluntary insurance through the Tervisekassa (which is quite expensive, often around 200+ euros per month) or look at private international health insurance. Many families find that How to Register Family Members for Health Insurance in Estonia is one of the more bureaucratic parts of the relocation process.
The Importance of the Digital Health Record
One of the reasons the social tax system works so efficiently is the Digilugu, or the Digital Health Record. Every time a doctor uses the funds provided by your social tax to treat you, the data is logged. You can see every test result, every prescription, and every doctor's note online.
When you use your social tax contributions to access care, you aren't just getting a one-off service. You are building a lifelong medical history that any doctor in the country can access (with your permission). This eliminates the need to carry folders of medical records from one clinic to another. Understanding How to Access My Digilugu Health Record Online in Estonia is essential for managing your long-term health in the country.
Common Pitfalls for Expats and Social Tax
The most common mistake is assuming that "residency" equals "insurance." You can have a residence permit, a rental apartment, and an ID card, but if no one is paying social tax on your behalf, you are not insured. Many expats live here for six months before realizing their "contractor" status with a foreign company meant they were responsible for their own taxes and, consequently, had no health coverage.
If you are working remotely for a company outside of Estonia, they aren't paying your Estonian social tax. You are effectively a freelancer in the eyes of the law. You must either set up a local entity or register as an FIE to pay the taxes yourself. If you don't, you won't appear in the Tervisekassa database. For these "nomad" types, SafetyWing is often the primary insurance provider because it fits the lifestyle of someone whose tax residency might be in one place, but whose physical presence is in Estonia.
Dealing with Lapses in Coverage
What happens if you lose your job? Your health insurance doesn't disappear the hour you get fired. Usually, your coverage continues for two months after the termination of your employment, provided you had been insured for at least six months prior. This "grace period" is funded by the social tax you've already paid. It gives you time to find a new job or register with the Töötukassa.
If you find yourself in a gap between jobs that lasts longer than two months, you must be very careful. This is a high-risk period. Many people forget to check their status on eesti.ee and only realize they are uninsured when they try to pick up a prescription. During these transitions, having a backup plan like SafetyWing is a literal lifesaver. It bridges the gap between your last social tax contribution and your next one, ensuring that a sudden illness doesn't become a financial catastrophe.
Navigating the Pharmacy System
Your social tax also subsidizes your medication. When a doctor issues a Digiretsept (digital prescription), the system automatically checks your insurance status. If you are covered via social tax, the pharmacy will apply a discount—often 50%, 75%, or even 90% depending on the medication and the illness.
Without active insurance, you pay the full price. For some specialized medications, the difference can be hundreds of euros. This is why Understanding the Digiretsept (Digital Prescription) System in Estonia is a core part of being a resident. You simply show your ID card at any pharmacy (Apteek), and they see your discounted rate immediately.
Conclusion and Strategic Advice for New Residents
The Estonian social tax system is a "set it and forget it" model for most employees, but it requires active management for the self-employed and those in transition. While it might feel painful to see 33% of a salary's value going to the state, the peace of mind that comes from a 5-euro specialist visit or a fully covered hospital stay is immense.
For any expat moving here, my advice is simple:
- Get your Isikukood immediately.
- Confirm your employer has registered you in the Employment Register.
- Check eesti.ee after 14 days to confirm your coverage is active.
- Keep a temporary policy like SafetyWing for your first month to cover the 14-day lag and any unforeseen paperwork delays.
By understanding How Estonia's Health Insurance Fund (Tervisekassa) Works: A Full Overview, you can navigate the system with confidence. Don't let the technical terms like "social tax" intimidate you; it is simply the price of entry into a digital society that takes care of its residents. Whether you are a developer in a high-rise in Maakri or a researcher in Tartu, your contributions are what keep this efficient, high-tech engine running for everyone.
Disclaimer
This guide is for informational purposes only and does not constitute legal, financial, or medical advice. Tax laws and healthcare regulations in Estonia are subject to change. Always consult with the Estonian Tax and Customs Board (MTA) or the Estonian Health Insurance Fund (Tervisekassa) for the most current and personalized information regarding your specific situation.