Understanding Pension Pillars (I, II, III) in Estonia
Let’s be honest, trying to wrap your head around a new country’s pension system is often one of the least glamorous, yet most crucial, tasks on an expat’s to-do list. You've probably found yourself staring at Estonian government websites, feeling a mix of confusion and existential dread about your future retirement. Don't worry, you’re not alone. This guide will walk you through Estonia's three-pillar pension system, cutting through the jargon to explain exactly how it works for us foreigners living and working here.
The Estonian Pension System: A Quick Overview for Expats
When you first arrive in Estonia, there's so much to figure out – getting your residence permit, finding a place to live, registering your address. The thought of pensions usually takes a backseat, often until you see those deductions on your payslip or hear colleagues discussing their "II Pillar" contributions. But ignoring it won't make it go away, and understanding it early can really help you plan your financial future here. Estonia’s pension system is designed to provide income security in old age, disability, and in the event of a breadwinner's death, just like back home. However, its structure, particularly the "three pillars," is unique and requires a bit of unpacking.
Why Pensions Matter for Expats in Estonia
It’s easy to think, "I'm only here for a few years," or "I'll sort out my pension when I move back home." But for many of us, "a few years" turns into a decade, and Estonia becomes a long-term home. Even if you don't plan to retire here, the contributions you make while working in Estonia contribute to your overall pension entitlement, both here and potentially back in your home country, thanks to international agreements. Ignoring your pension here means potentially leaving money on the table or not adequately planning for your golden years. It's not just about what you get when you retire; it's about understanding what financial safety nets are being built for you right now.
Moreover, if you are planning to settle down, perhaps start a family, or even run your own business, then understanding how your contributions translate into future benefits becomes absolutely critical. The system is set up to reward consistent contributions, and even if you leave Estonia, these contributions don't just vanish into thin air. Many expats find themselves surprised by how quickly their life in Estonia takes root, making long-term financial planning, including pensions, an essential part of becoming truly settled.
The Basic Principles and Philosophy
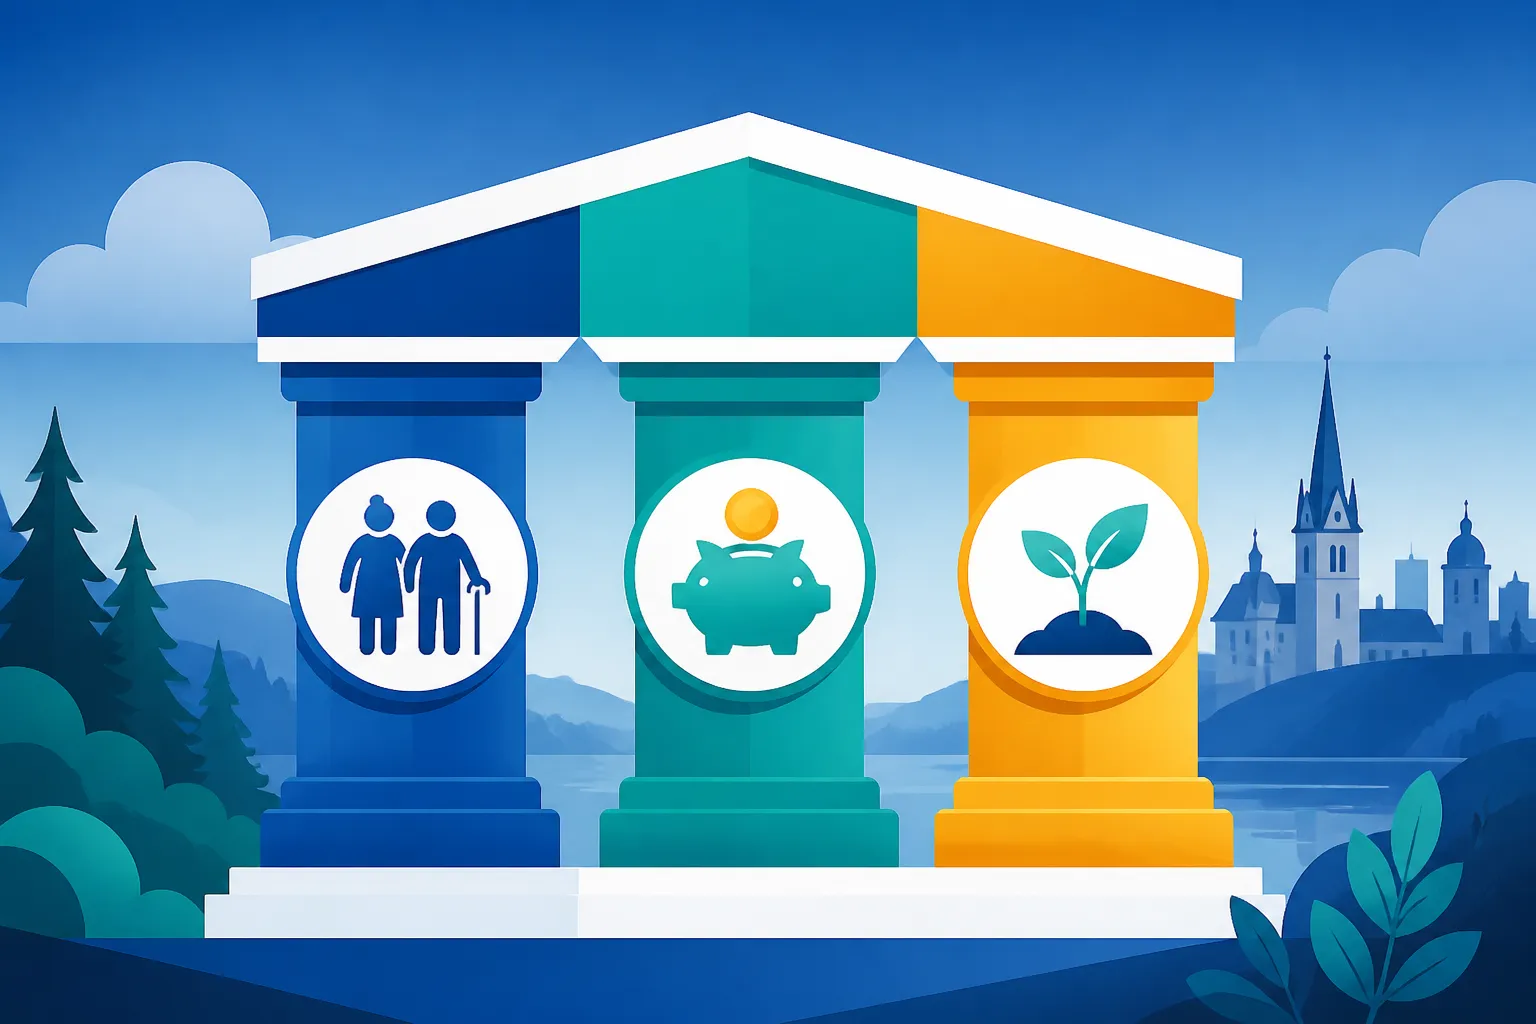
Estonia’s pension system is built on a "three-pillar" model, a common structure in many European countries designed to diversify risk and provide multiple layers of security. The philosophy behind this approach is to avoid relying solely on one type of funding (e.g., state-funded pay-as-you-go) and to empower individuals to take a more active role in their retirement savings.
The First Pillar is essentially a state pension, paid from current social tax contributions, and it's the foundation. It provides a basic safety net for everyone who has contributed. The Second Pillar introduces a mandatory funded element, where a portion of your social tax is diverted into personal investment funds. This aims to build up a capital-based pension for you. Finally, the Third Pillar is entirely voluntary, offering additional private savings opportunities, often with tax incentives, for those who want to supplement their retirement income further. This multi-layered approach aims to create a more robust and sustainable system than relying on a single, often strained, state fund.
Pillar I: The State Old-Age Pension (First Pillar)
This is the bedrock of the Estonian pension system, often referred to as the "national pension" or "state old-age pension." It’s a pay-as-you-go system, meaning the social tax contributions made by current workers and employers fund the pensions of today's retirees. Think of it as a solidarity pact between generations. As an expat, if you're working legally in Estonia and paying social tax, you're automatically contributing to and covered by this pillar.
Who is Covered and How it Works
Anyone legally employed in Estonia, whether under an employment contract or as a self-employed individual (FIE or OÜ owner paying themselves a salary), contributes to the First Pillar through their social tax payments. This also extends to those receiving certain benefits, like parental benefits, ensuring continuous contribution periods. The Estonian social tax, or sotsiaalmaks, is a hefty 33% of your gross salary (paid by the employer on top of your gross salary or by the FIE on their declared income). A portion of this social tax (specifically, 20% goes to the state pension insurance and 13% to health insurance) funds the First Pillar. This system aims to provide a basic level of income in retirement, ensuring that everyone who has contributed adequately receives a pension.
For expats, the key is understanding that your contributions here accumulate, just like they would for an Estonian citizen. The amount you eventually receive from the First Pillar is largely dependent on your length of service (how many years you’ve paid social tax in Estonia) and your average income during those years. Even if you don't spend your entire career in Estonia, these years count. Estonia has social security agreements with many countries, including all EU/EEA member states, which means your pension periods accumulated in Estonia can often be combined with periods from other countries when calculating your overall pension entitlement. This is a huge relief for those of us who move around a lot for work. You can usually find information on your social tax contributions via the e-MTA online tax portal, which can be invaluable for tracking your progress. For a deeper dive into how your social tax contributions actually translate into health coverage, you might want to read about Understanding Health Insurance Through Social Tax in Estonia.
Calculating Your First Pillar Pension
The calculation of the First Pillar pension is based on several components: the basic part, the insurance part, and the solidarity part. The basic part is a fixed sum that everyone who meets the minimum service requirement receives. The insurance part depends on your "pension capital," which is essentially a sum derived from your social tax payments and how they compare to the national average over your working life. The solidarity part considers the number of years of service prior to 1999, which is less relevant for most new expats but still part of the overall formula.
The minimum qualifying period to receive an Estonian old-age pension is 15 years of pensionable service, though the full state pension generally requires 40-44 years depending on your birth year. If you have fewer than 15 years in Estonia but have accumulated periods in other countries with which Estonia has an agreement, these periods can be considered under EU regulations or bilateral agreements. It’s complex, but the general rule is: the longer you’ve contributed, and the higher your income (leading to higher social tax payments), the larger your First Pillar pension will be. This makes long-term tax planning and understanding your income vital. You can get a good overview of the general tax landscape in The Complete Guide to Taxes in Estonia for Expats (2027).
Challenges and Considerations for Expats
One of the biggest challenges for expats is understanding how their Estonian pension contributions will interact with pension systems in their home country or other countries where they've worked. While EU regulations simplify this significantly for EU citizens, those from non-EU countries need to investigate bilateral social security agreements between Estonia and their home country. Without such an agreement, combining pension periods can be much more difficult, potentially leading to lost benefits or fragmented pensions.
Another consideration is the pension age. Estonia's state pension age is gradually increasing and is linked to life expectancy, meaning it will likely be 65 for those born in 1962 and later, subject to review. This might differ from your home country’s pension age, requiring careful planning. Furthermore, if you only contribute for a short period in Estonia, your First Pillar pension might be quite small, highlighting the importance of the Second and Third Pillars, or ensuring robust pension planning in your primary country of residence. It's a complex area, and sometimes consulting with a financial advisor specializing in cross-border pensions or platforms like Taxes for Expats can be incredibly useful to ensure you’re not caught off guard.
Pillar II: The Mandatory Funded Pension (Second Pillar)
The Second Pillar, also known as the "mandatory funded pension," adds a crucial element of personal savings and investment to Estonia's retirement system. This pillar is designed to accumulate capital specifically for your retirement, rather than relying solely on the pay-as-you-go system of Pillar I. It's a significant component, often discussed among locals, and understanding its nuances is key for expats planning their long-term finances here.
Understanding Contributions and Opting In/Out
For most employed individuals in Estonia, contributions to the Second Pillar are mandatory. It works like this: 2% of your gross salary is deducted directly from your pay, and this is then topped up by 4% from the social tax paid by your employer (which would otherwise go fully to the First Pillar). So, in essence, 6% of your gross salary (2% from you, 4% from your employer's social tax contribution) is diverted into a personal pension fund. This mechanism ensures a steady stream of capital building up over your working life.
However, there are exceptions and historical factors. Until 2021, the Second Pillar was generally mandatory for most new workers who entered the system. A reform introduced an option for people to opt out or even withdraw their accumulated funds, a decision that has sparked considerable debate. While you are generally enrolled automatically if you start working in Estonia and meet the criteria, you now have the possibility to make a choice. Opting out means those 6% contributions will revert to the First Pillar, potentially increasing your future state pension but sacrificing the personalized investment growth of Pillar II. This choice isn't to be taken lightly, as it significantly impacts your long-term retirement savings strategy. You also need an Isikukood (personal code) to manage your pension accounts, so understanding how to get your Isikukood and register with the Estonian Tax Board is a foundational step for any financial planning here.
Investment Choices and Fund Management
Once your contributions start flowing into the Second Pillar, they are invested in pension funds managed by various financial institutions in Estonia. Unlike the First Pillar, where your money is simply part of a collective pool, in Pillar II, you choose a specific pension fund. These funds come with different risk profiles – from conservative (investing mainly in bonds) to aggressive (heavy on equities). The choice is yours, and it’s important to research and select a fund that aligns with your risk tolerance and investment horizon. Popular providers include banks like Swedbank, SEB, and LHV, as well as independent fund managers.
The performance of your Second Pillar fund directly impacts the amount of capital you will have at retirement. You can usually change your fund manager or fund type a few times a year. Many expats appreciate this element of control, as it allows them to be more active participants in their retirement planning, especially if they have some investment experience. Regularly checking your fund's performance and adjusting your strategy if needed is a wise move. You can typically access your pension fund information and make changes through your bank's online portal or dedicated pension portals.
Portability and Early Withdrawal Implications
For expats, the question of portability is crucial. If you leave Estonia permanently before retirement, what happens to your Second Pillar funds? Under current regulations, if you are moving within the EU/EEA, these funds are generally not directly transferable to another country's pension system. They remain in Estonia until you reach Estonia's pensionable age, at which point you can claim them, regardless of where you reside. However, if you have opted out of the Second Pillar (a possibility introduced in 2021), you may have different options, including the ability to withdraw accumulated funds as a lump sum, though this typically incurs a significant income tax.
The decision to withdraw funds early comes with major tax implications. A significant portion of the withdrawn amount will be subject to income tax. This option, while seemingly attractive for immediate liquidity, can seriously diminish your long-term retirement savings and should be carefully considered. It often means sacrificing potential investment growth and compounding returns that could have significantly increased your retirement pot. Understanding these penalties is a critical part of knowing your overall tax obligations, a topic comprehensively covered in Filing Your Annual Tax Return in Estonia: The Complete Walkthrough (2027).
Pillar III: The Supplementary Funded Pension (Third Pillar)
While the First Pillar is your basic state safety net and the Second Pillar is your mandatory personal investment, the Third Pillar is where you really take the reins. This is an entirely voluntary system designed for those who want to actively supplement their retirement income beyond what the first two pillars will provide. It’s particularly appealing due to its flexibility and the generous tax incentives offered by the Estonian state.
Voluntary Savings and Investment Options
The Third Pillar offers a wide array of options, primarily through two main vehicles: a supplementary pension fund (similar to Pillar II funds, but voluntary) or a long-term savings insurance contract offered by insurance companies. With pension funds, you once again choose a fund manager and a risk profile that suits you, with your contributions invested in stocks, bonds, and other assets. Long-term savings insurance, on the other hand, typically offers more guarantees and potentially a slightly different investment structure.
What's great about the Third Pillar is its flexibility. You decide how much and how often you contribute – whether it's a fixed monthly sum, irregular top-ups, or even lump-sum payments. This allows you to tailor your savings strategy to your current financial situation and future goals. For expats who might have a shorter time horizon in Estonia or specific financial goals, this flexibility can be a major advantage compared to more rigid systems. Many use it to bridge potential gaps in their cross-border pension coverage or simply to accelerate their retirement savings.
Tax Incentives and Benefits
One of the most attractive features of the Third Pillar, and why many locals and long-term expats participate, are the significant tax benefits. Contributions to the Third Pillar are eligible for income tax deduction. You can deduct up to 15% of your annual income, but not more than €6,000 per year, from your taxable income. This means a portion of your contributions is effectively paid for by a tax refund. For instance, if you contribute €1,000 to your Third Pillar fund and your income tax rate is 20%, you could get €200 back from the tax authorities. This makes it a very efficient way to save for retirement.
However, the tax benefit is primarily on the contribution side. When you eventually withdraw your Third Pillar funds, the payouts are subject to income tax, though often at a reduced rate (e.g., 10% if withdrawn at state pension age or in case of permanent incapacity for work, compared to the standard 20% income tax). There are specific rules around withdrawal to maintain these tax benefits, generally requiring you to be at state pension age or facing certain life events. Early withdrawals not meeting these criteria may be subject to the full income tax rate. It’s always a good idea to consult tax advisors, perhaps those specializing in Taxes for Expats, to understand the precise implications for your specific situation, especially if you have a complex tax residency status. To learn more about navigating your overall tax obligations in Estonia, you can check out Understanding Tax Residency Rules for Expats in Estonia.
Is the Third Pillar Right for You?
Deciding whether to participate in the Third Pillar really depends on your individual circumstances, financial goals, and risk appetite. If you plan to stay in Estonia long-term, want to maximize your retirement savings, and take advantage of the tax incentives, it's definitely worth considering. It offers a way to compound your wealth over time and gives you greater control over your investment strategy.
For expats with shorter planned stays, the decision is a bit more nuanced. While the tax benefits are attractive, the funds are tied up until retirement age (or specific conditions), and their portability abroad can be complex, often meaning you claim them from Estonia later. However, if you view it as part of a broader global retirement strategy, even a few years of tax-advantaged saving can make a difference. It's a fantastic tool for those looking for supplementary income and additional financial security, complementing the base provided by Pillars I and II.
Comparing the Pillars: A Holistic View
Understanding each pillar in isolation is one thing, but seeing how they fit together is crucial for building a comprehensive retirement plan in Estonia. Each pillar serves a distinct purpose, has different funding mechanisms, and comes with its own set of rules and benefits. For expats, a clear comparison helps in making informed decisions about your financial future in Estonia and beyond.
Here's a quick comparison to give you the lay of the land:
| Feature | Pillar I: State Old-Age Pension (First Pillar) | Pillar II: Mandatory Funded Pension (Second Pillar) | Pillar III: Supplementary Funded Pension (Third Pillar) |
|---|---|---|---|
| Nature | Pay-as-you-go, state-funded | Mandatory personal investment | Voluntary personal investment |
| Funding | Social tax from active workers (33% from employer) | 2% from gross salary (employee) + 4% from social tax (employer) | Self-funded contributions (flexible amounts) |
| Management | State (Social Insurance Board) | Private pension funds (chosen by individual) | Private pension funds or insurance (chosen by individual) |
| Risk | Political/demographic (state solvency) | Investment market risk, fund performance | Investment market risk, fund performance |
| Flexibility | Low (fixed state rules) | Moderate (fund choice, opt-out option since 2021) | High (contribution amounts, fund choice, withdrawal) |
| Tax Benefits | None directly for contributions | None directly for contributions | Income tax deduction for contributions (up to €6k/year or 15% of income) |
| Withdrawal | At state pension age, based on service/income | At state pension age, lump sum or annuities (taxed) | At state pension age (reduced tax), or earlier (full tax) |
| Expat Relevance | Base security, international agreements | Personal capital accumulation, portability nuances | Flexible savings, tax benefits, complements other pillars |
Key Differences and Interdependencies
The most glaring difference is the funding mechanism. Pillar I is a collective pool, dependent on current taxpayers, while Pillars II and III are funded by your direct or indirect contributions into individual investment accounts. This means Pillar I is susceptible to demographic shifts and economic policy changes, whereas Pillars II and III are more exposed to market fluctuations but also offer the potential for higher returns.
Pillar I forms the foundation. Without consistent social tax payments, your eligibility for a basic state pension can be jeopardized. Pillar II then builds upon this, diverting a portion of what would have gone to Pillar I into your personal investment portfolio, aiming to provide a more substantial, capital-based pension. The choice to opt-out of Pillar II effectively means all your social tax contributions go to Pillar I. Finally, Pillar III is completely independent in terms of contributions, but it's often viewed as a way to enhance the income derived from the first two, making your overall retirement pot more robust. While independent, they're interdependent in the sense that a strong First Pillar provides a baseline, allowing you to take more calculated risks with the investment-driven Pillars II and III.
Planning Your Retirement Strategy in Estonia
For expats, a truly effective retirement strategy in Estonia involves much more than just these three pillars. It requires a holistic view that integrates your Estonian pension entitlements with any pension schemes from previous countries of residence, private investments, and personal savings. You need to consider your expected length of stay in Estonia, your career trajectory, and your eventual retirement destination.
If you envision a long-term future in Estonia, maximizing contributions to all three pillars can be a sound strategy, particularly leveraging the tax benefits of Pillar III. If your stay is shorter, focusing on ensuring Pillar I contributions are correctly recorded and understanding the withdrawal rules for Pillar II (should you choose to participate) become paramount. Don't forget other forms of savings – personal investments, real estate, or other financial products. Services like Wise can be helpful for managing funds across borders, ensuring seamless transfers between your Estonian accounts and those in other countries as part of your broader financial planning. For more comprehensive insights into your earnings and what exactly gets deducted, check out Understanding Gross vs Net Salary and Payslips in Estonia.
Navigating Pensions as a Foreigner: Key Takeaways
The Estonian pension system, with its three pillars, offers a robust framework for retirement savings. As an expat, understanding these pillars and how your contributions accumulate is crucial for informed financial planning. It might seem daunting at first, but with a bit of research and proactive management, you can ensure your time working in Estonia contributes meaningfully to your future security.
The Importance of Your Isikukood and Social Tax
Your Isikukood (personal identification code) is the cornerstone of virtually all administrative and financial processes in Estonia, and pensions are no exception. Every social tax payment you make, every contribution to Pillar II, and every voluntary payment to Pillar III is meticulously linked to your Isikukood. Without it, your contributions cannot be properly recorded, and you risk not receiving credit for your pensionable service. Similarly, understanding Social Tax (Sotsiaalmaks) Contributions in Estonia is vital, as this is the engine that drives your Pillar I and partly your Pillar II contributions. Ensure your employer is correctly paying social tax on your behalf, or if you're self-employed, that you are fulfilling your obligations. These seemingly minor administrative details are paramount to securing your future pension entitlements.
Seeking Professional Advice and Cross-Border Considerations
Pension planning is rarely a "one size fits all" scenario, and for expats, it's even more complex due to cross-border implications. While this guide provides a detailed overview, it's not a substitute for personalized financial or legal advice. Consider consulting with a financial advisor who specializes in expat finances or cross-border pension planning. They can help you:
- Integrate your Estonian pension with schemes from other countries. This is particularly important for non-EU citizens or those with complex career histories.
- Evaluate your risk tolerance and investment strategy for Pillars II and III.
- Understand the tax implications of withdrawals or transferring funds, both in Estonia and your home country.
- Plan for potential gaps in your pension coverage if you move frequently between countries.
There are many resources available, from the Estonian Social Insurance Board (Sotsiaalkindlustusamet) to private financial advisors. Many professionals are well-versed in assisting foreigners. Don't hesitate to reach out if you have specific questions or a unique situation. Planning for retirement, especially as a mobile individual, is a journey, not a sprint, and having expert guidance along the way can make all the difference. For those who are just starting their professional journey here, knowing how the pension system aligns with the broader employment landscape can be very beneficial, so perhaps looking at The Complete Guide to Working in Estonia as a Foreigner (2027) could be your next step.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute financial, legal, or tax advice. While every effort has been made to ensure accuracy and timeliness, pension laws and regulations in Estonia, as well as international agreements, can change. Expats should consult with a qualified financial advisor, tax professional, or the relevant Estonian authorities for advice tailored to their individual circumstances.